Live Chat

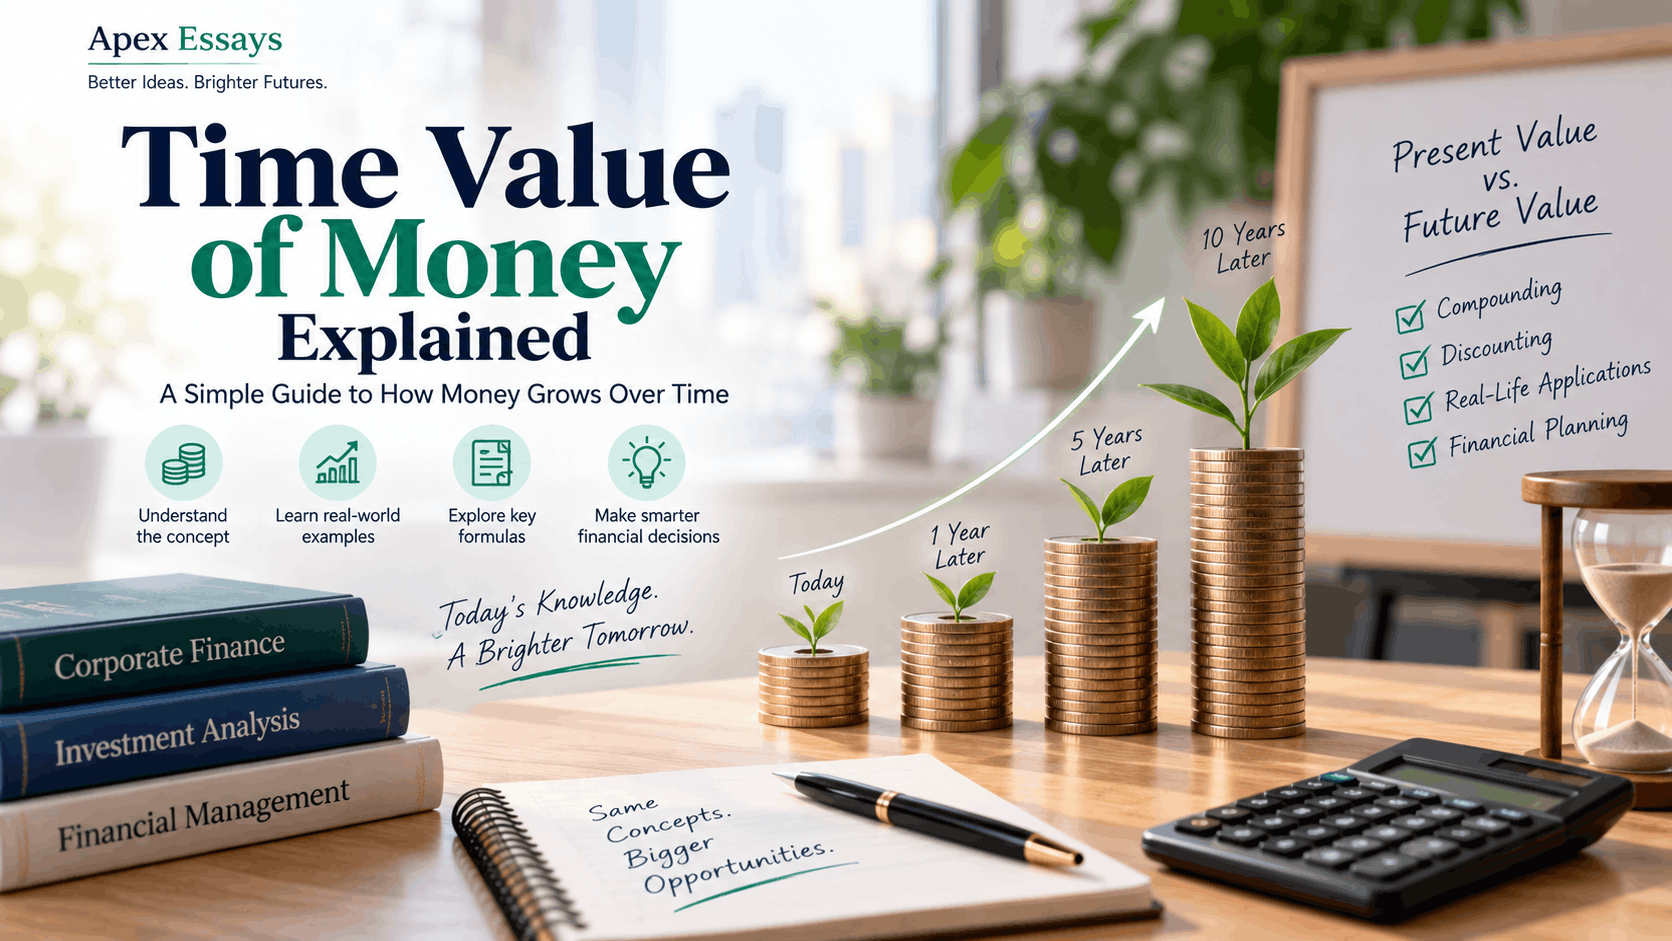
A dollar you hold now is worth more than a dollar promised later, because the one you hold can be earning something in the meantime. Every calculation in a time value of money problem set is that one sentence turned into arithmetic, and there is really only one formula underneath all of it: a dollar moved forward in time gets multiplied by (1 + r), and a dollar moved backward gets divided by it. Future value multiplies. Present value divides. Annuities do the same thing several times and add up the results.
Which means the formula is almost never what costs you the points. The setup does — the rate that did not match the period, the payment that arrives at the start of the year instead of the end, the growth rate attached to last year's cash flow instead of next year's. This walks through each calculation with the arithmetic printed out, and then through the six setup errors that produce a wrong answer from a formula you copied correctly.
- One idea, two directions. Compounding pushes a cash flow forward and multiplies by (1 + r)n; discounting pulls it back and divides by the same thing.
- An annuity factor is not a new formula. It is the sum of the individual lump-sum factors, collapsed into one expression so you do not have to write six lines.
- Compounding frequency has to be applied twice — to the rate and to the number of periods. Half of the adjustment is worse than none, and the version that looks most reasonable is the one that quietly loses points.
- An annuity due is an ordinary annuity times (1 + r), and that single multiplier fixes both the present value and the future value.
- A perpetuity is a division, not a summation. Payment divided by rate, and for a growing perpetuity, next period's payment divided by (r − g).
- Textbook table factors are rounded to three decimals, so a table answer and a calculator answer will differ by a few cents. Neither is wrong.
The one equation everything else is built from
OpenStax's Principles of Finance puts the underlying idea plainly: the time value of money is predicated on the fact that it is possible to earn interest income on cash that you decide to deposit in an investment or interest-bearing account.
Money left alone for a period comes back larger by the rate it earned.
Do that for one period and you multiply by (1 + r). Do it for n periods and each period compounds on the last, so you multiply by (1 + r)n. That is future value:
FV = PV × (1 + r)n
Present value is the same equation read right to left. If multiplying moves a dollar forward, dividing moves it back:
PV = FV ÷ (1 + r)n
That division is what discounting means. It is not a separate technique; it is compounding run in reverse, and the number you divide by is called the discount factor.
Forward. $4,000 invested at 6% for 5 years, compounded annually. 1.065 = 1.338226, so FV = $4,000 × 1.338226 = $5,352.90.
Backward. You need $9,000 in 4 years and can earn 7%. 1.074 = 1.310796, so the discount factor is 1 ÷ 1.310796 = 0.762895, and PV = $9,000 × 0.762895 = $6,866.06. Deposit that today and you have $9,000 in four years.
A finance problem set is mostly four questions dressed up in different sentences: what will this grow to, what is that worth today, what is a stream of these worth, and which of two streams is bigger. The first two are the formulas above. The third is an annuity. The fourth is what net present value does with them, and that is its own topic.
Compounding frequency: the adjustment you have to make twice
Interest is rarely credited once a year. A car loan compounds monthly, a bond pays semiannually, a savings account may compound daily. When it does, two things change together, and missing either one is a common source of wrong answers.
Let m be the number of compounding periods in a year. The stated annual rate is a nominal rate, so:
- the rate per period becomes r ÷ m, and
- the number of periods becomes n × m, where n is now years.
FV = PV × (1 + r/m)m×n
Both halves, every time. Here is the same problem — $4,000, 6% nominal, 5 years, compounded monthly — solved four ways: correctly, and then with each half of the adjustment missing.
| What you did | Rate used | Periods used | Answer | Off by |
|---|---|---|---|---|
| Correct — both adjusted | 0.005 | 60 | $5,395.40 | — |
| Divided the rate, forgot the periods | 0.005 | 5 | $4,101.01 | −$1,294.40 |
| Multiplied the periods, forgot the rate | 0.06 | 60 | $131,950.76 | +$126,555.36 |
| Ignored the frequency entirely | 0.06 | 5 | $5,352.90 | −$42.50 |
Look at the last two rows, because they are the actual lesson. Multiplying the periods without dividing the rate turns a $4,000 deposit into $131,950.76, roughly thirty-three times what went in, which anyone catches on sight. Ignoring the frequency entirely produces $5,352.90, which is $42.50 low on $5,395.40, under one percent. It looks completely reasonable, and it survives the order-of-magnitude check that catches the row above it. What it does not survive is a check on direction: compounding monthly has to beat compounding annually, and $5,352.90 is the annual answer — the same $4,000 at 6% for five years worked at the top of this article. Run that comparison and the row gives itself away. Skip it, and this is the one that gets marked wrong.
Say the unit out loud before you write anything: "the period is one month, the rate is 0.5% per month, there are 60 months." If every one of the three ends in the same word, the setup is right. A rate in years next to a count in months is the whole bug.
Nominal rate, effective rate, and the two laws that separate them
Once compounding happens more than once a year, a 6% rate does not earn 6%. Run the monthly version out for a full year: (1.005)12 = 1.06167781, so the account grows 6.1678%. That is the effective annual rate, and the general form is:
EAR = (1 + r/m)m − 1
| Compounding on a 6% nominal rate | Effective annual rate |
|---|---|
| Annually | 6.0000% |
| Quarterly | 6.1364% |
| Monthly | 6.1678% |
| Daily (365) | 6.1831% |
Textbooks usually stop there. The distinction is not a classroom convention, though — US federal law encodes both sides of it, in two separate rules you can go and read.
For credit cards and other open-end credit, Regulation Z says that where a periodic rate is used to compute the finance charge, the annual percentage rate must be computed by multiplying each periodic rate by the number of periods in a year
(12 CFR 1026.14(b)). That is a nominal rate by construction: a 0.5% monthly periodic rate is disclosed as a 6% APR, and the compounding is not in the number.
For deposit accounts, Regulation DD goes the other way. Its Appendix A (12 CFR part 1030) opens by saying the annual percentage yield measures the total amount of interest paid on an account based on the interest rate and the frequency of compounding
, and prescribes the formula APY = 100[(1 + Interest/Principal)(365/Days in term) − 1]. That is an effective annual rate wearing a different name.
The appendix then works an example: If an institution pays $61.68 in interest for a 365-day year on $1,000 deposited into a NOW account, using the general formula above, the annual percentage yield is 6.17%
. Where does $61.68 come from? The appendix does not say. It builds the example from a dollar amount of interest, not from a rate, and it reaches 6.17% a second way that assumes nothing about compounding at all — it simply divides the interest by the principal. But $61.68 is exactly what $1,000 earns at 6% nominal compounded monthly: $1,000 × (1.00512 − 1) = $61.6778. None of the other frequencies a course uses lands there — annual pays a flat $60.00, semiannual $60.90, quarterly $61.36, daily $61.83. So the setup your textbook sets — 6% nominal, monthly compounding, 6.17% effective — reproduces the regulation's own example to the cent, whether or not that is where the drafters got it.
So when a problem hands you an APR and asks for a monthly payment, divide by 12. When it hands you an APY and asks the same thing, do not — the compounding is already inside that number, and you need to strip it back out first. Reading which of the two you were given is half of the question.
Annuities: the same discounting, done several times
Most problem sets are not lump sums. They are rent, loan payments, contributions, dividends — the same amount arriving on a schedule. OpenStax's managerial accounting volume defines it exactly as the algebra does: annuities are a series of equal payments made over time, and ordinary annuities pay the equal installment at the end of each payment period within the series.
Here is the thing textbooks rarely stop to say. The annuity formula is not new information. It is six lump-sum calculations added together and then compressed. Take $2,500 a year for 6 years at 5%, and discount each payment on its own:
| Payment arrives at | Calculation | Present value |
|---|---|---|
| End of year 1 | $2,500 ÷ 1.051 | $2,380.95 |
| End of year 2 | $2,500 ÷ 1.052 | $2,267.57 |
| End of year 3 | $2,500 ÷ 1.053 | $2,159.59 |
| End of year 4 | $2,500 ÷ 1.054 | $2,056.76 |
| End of year 5 | $2,500 ÷ 1.055 | $1,958.82 |
| End of year 6 | $2,500 ÷ 1.056 | $1,865.54 |
| Total | — | $12,689.23 |
Now the closed form, which does the identical work in one line:
PVannuity = PMT × [1 − (1 + r)−n] ÷ r
[1 − 1.05−6] ÷ 0.05 = 5.075692, and $2,500 × 5.075692 = $12,689.23. The same number, because it is the same six divisions.
Future value works the same way, compounding each payment forward to the end instead of back to today:
FVannuity = PMT × [(1 + r)n − 1] ÷ r
[(1.05)6 − 1] ÷ 0.05 = 6.801913, so FV = $2,500 × 6.801913 = $17,004.78. And because both describe the same six payments, the two must agree: $12,689.23 × 1.056 = $17,004.78 exactly. If your PV and FV do not reconcile that way, one of them has the wrong n.
Ordinary annuity or annuity due — where the (1 + r) goes
Everything above assumed payments land at the end of each period. OpenStax states the default plainly: An ordinary annuity is one in which the payments are made at the end of each period in equal installments.
Loan payments and coupon payments usually work this way.
Rent does not. Neither do lease payments, insurance premiums, or a deposit you make today. Those arrive at the beginning, and OpenStax names that case too: With annuities due, the cash flow occurs at the start of the period.
Every payment therefore sits one full period earlier than the ordinary version, so every payment gets one less period of discounting — or one more period of compounding. One multiplier fixes it, and it is the same multiplier for both present and future value:
Annuity due = ordinary annuity × (1 + r)
| $2,500 for 6 years at 5% | Ordinary (end of period) | Due (start of period) | Difference |
|---|---|---|---|
| Present value | $12,689.23 | $13,323.69 | $634.46 |
| Future value | $17,004.78 | $17,855.02 | $850.24 |
That $634.46 is not arbitrary: it is exactly 5% of $12,689.23, which is what "one period earlier" is worth at a 5% rate.
Compute the annuity due a second way. Six payments starting today = one payment right now, undiscounted, plus an ordinary five-payment annuity behind it. That is $2,500 + ($2,500 × 4.329477) = $2,500 + $10,823.69 = $13,323.69. Same figure, different route. If the two routes disagree, you applied (1 + r) twice — usually because you used a calculator already set to BGN mode and multiplied by hand.
Perpetuities: when the payments never stop
A perpetuity is an annuity with no end date — a preferred dividend, an endowment payout, a British consol. You would expect an infinite stream to be worth an infinite amount. It is not, because payments far enough out are discounted almost to nothing, and the series converges. Iowa State University Extension states the result in one sentence in its Understanding the Time Value of Money file (updated March 2023): The present value of a perpetuity is the payment divided by the discount rate.
PVperpetuity = PMT ÷ r
$2,500 a year forever at 5% is $2,500 ÷ 0.05 = $50,000. Compare that with the six-year version's $12,689.23 and you can see how quickly the later payments stop mattering: the twenty-fifth year contributes under $740 of it.
If the payment grows at a constant rate g, the denominator shrinks by that growth:
PVgrowing = C1 ÷ (r − g)
That numerator is C1 — the payment one period from now, not the one just made. If a problem says "the dividend just paid was $2,500 and grows 2% a year," C1 is $2,550, and the answer is $2,550 ÷ 0.03 = $85,000. Using $2,500 gives $83,333.33. One word in the question — paid versus will pay — moves the answer by $1,666.67.
Also: the formula only holds when g is smaller than r. If a problem hands you a growth rate above the discount rate, it is testing whether you notice.
A setup routine that removes most of the errors
Before touching a formula, spend thirty seconds doing this. It is faster than redoing the problem.
A line, tick marks for periods, arrows for cash in and out. A payment landing in the wrong place is obvious on a sketch and invisible inside an equation.
Month, quarter, half-year, year. Everything after this has to be expressed in that unit — no exceptions.
Divide the nominal annual rate by the number of those periods in a year. Write the result down as a decimal so you cannot confuse 6% with 0.06 with 0.005.
Years times periods per year. Five years of monthly compounding is 60, not 5.
One cash flow or many? If many, do they land at the end of each period or the beginning? That single answer decides whether you multiply by (1 + r) at the end.
Six setup mistakes that produce a wrong answer from a right formula
These are the ones worth checking for by name when a number comes out strange. They are not in any particular order — check whichever fits the symptom.
| Mistake | What it looks like | How to catch it |
|---|---|---|
| Half-adjusted compounding | The rate is divided by 12 but n is still in years, or the reverse | Rate, count and period must all name the same unit |
| Nominal used as effective | An APY plugged in where a periodic rate belongs | APR divides cleanly by m; APY does not |
| Timing missed | Rent, lease or "starting today" treated as an ordinary annuity | Read for beginning, today, in advance; then multiply by (1 + r) |
| (1 + r) applied twice | Calculator in BGN mode and a manual multiply | Cross-check by the one-payment-now route |
| Growth attached to the wrong cash flow | C0 used where C1 belongs in a growing perpetuity | "Just paid" means grow it once before dividing |
| Discounting to the wrong date | An annuity starting in year 4 discounted straight to today | The formula lands the value one period before the first payment; discount that lump sum the rest of the way back |
The last one is the sneakiest, because the annuity formula does not put the value at today. It puts it at the period immediately before the first payment. For an ordinary annuity whose first payment is at t = 1, that happens to be t = 0, which is why it usually looks like it works automatically. For a deferred annuity whose first payment is at t = 4, the formula lands the value at t = 3, and you still have three years of discounting left to do.
Knowing all of that does not make a forty-problem set any shorter, and this is usually the point in the semester where the mechanics are clear and the calendar is not. If that is the wall you have hit, our finance homework help works the sets with the setup line shown for every problem, so what comes back is something you can follow and check rather than a page of final answers.
Why your answer does not match the back of the book
You do the problem, get $5,195.37, and the solutions say $5,194.80. Nothing is wrong. Older textbooks and many exam appendices use factor tables, and those factors are rounded to three decimal places.
OpenStax's managerial accounting chapter shows this in its own worked examples. For a five-year loan at 5% with $1,200 annual payments, it uses a present value factor of 4.329 and gets $5,194.80. The unrounded factor is 4.329477, which gives $5,195.37 — a 57-cent gap that is entirely the rounding. The same chapter's retirement example uses a future value factor of 37.280 on $10,000 a year for 15 years at 12% and prints $372,800; the exact figure is $372,797.15, off by $2.85.
Match the method the assignment expects. If you were given a table, use the table's factor and its rounding. If you were told to use a financial calculator or a spreadsheet, use full precision. Then say which you used — a one-line note ("PV factor from Table A-2, three decimals") turns a discrepancy into a documented choice rather than an unexplained mismatch.
Putting it together
Every one of these formulas is the same move repeated. Multiply to go forward, divide to come back, add the results when there are several, and use a closed form when adding by hand gets tedious. The algebra is short. What takes the practice is reading a paragraph of English and deciding which cash flow lands where, at what rate, in which unit.
So when a problem comes out wrong, resist rechecking the formula first. Go back to the sketch and check the four things that decide everything: the period, the rate expressed in that period, the count expressed in that period, and whether the money moves at the start or the end. Fix those and the arithmetic almost always follows — which is also why these mechanics are the first thing a capital budgeting or cost of capital chapter assumes you already have.